This morning, following a big tech selloff overnight, Jacob Reynolds sent out a memo to all Courtiers Advisers. Shortly after, Leo called him.
Tune in to hear Jake’s take on the recent activity hitting our headlines – and the markets – and see his memo below:
Fri 2026-11-06 11:35
From: Jacob Reynolds
To: All Courtiers Advisers
What an eventful two weeks: the Budget, BoE meetings, and culminating in the US midterms.
Markets initially responded well to the potential for less Trump chaos and lower oil prices. However, that excitement turned into fear as concerns grew that the incoming administration might not be as market-friendly, particularly toward a very concentrated trade in the market.
I think the attitude is best summarised by newly elected Ohio Senator, Sherrod Brown, after the Democrats flipped the seat in the midterms:
“I do not work for data centres. I do not work for Wall Street.”
(This was JD Vance’s former seat, which was held by Republican appointee Jon Husted until this week.)
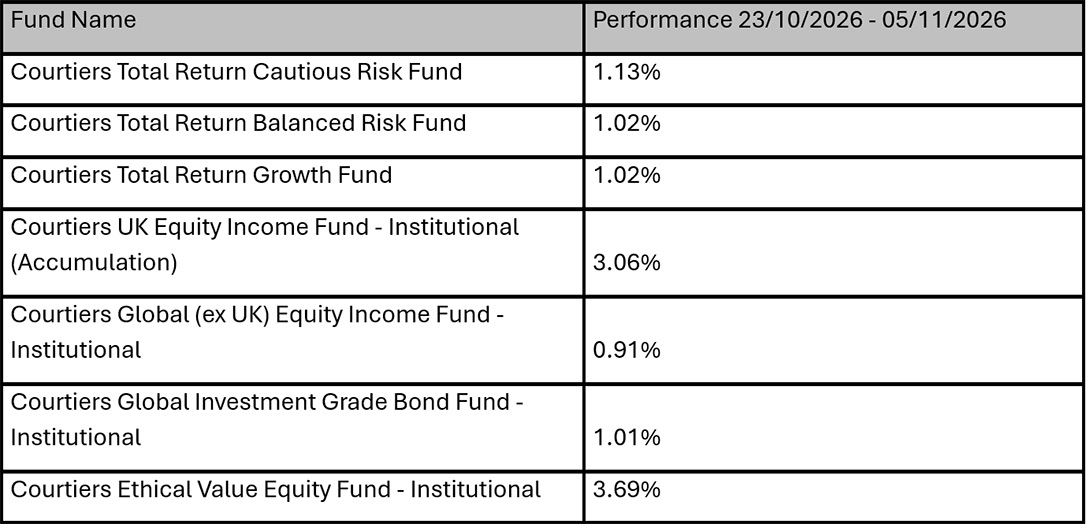
The Nasdaq fell -6.50% last night and is down -8.03% over the last two weeks. The S&P 500 fell -4.36% last night and is down -3.52% over the last two weeks. The MSCI World fell -3.28% last night and is down -2.32% over two weeks. Every single Courtiers fund is up over this exact timeframe.
The current US weighting in the MSCI World stands at 72.77% and remains heavily concentrated in the big tech/AI/data centre trade. As we noted back in 2024 when we shifted a portion of our S&P 500 exposure to the equal-weighted index to limit concentration risk, “being prudent pays.”
Courtiers funds still maintain a ~40% equity allocation to the US, but it is broadly diversified and includes value stocks, individual equities, and smaller companies.
Jacob Reynolds CFA, CQF
Asset Management Director
Transcript
Jacob Reynolds (Asset Management Director)
Hello, Leo.
Leo Hallam (Head of Marketing)
Hi, Jake. Can you talk?
Jacob Reynolds
I can, yeah.
Leo Hallam
Good. Thank you. The world’s been keeping you guys really busy over the last couple of weeks, and I wanted to catch up and get your take on it.
We’ve had the budget. We’ve had the BoE (Bank of England) increasing the interest rates, and now we’ve had this big tech selloff overnight.
What’s your take on everything?
Jacob Reynolds
Well its been an incredible, incredibly eventful couple of weeks. Like you said it started off with the budget last Wednesday. That wasn’t the explosive budget that we feared. It was actually very, very tame and expected. And we had the bank tariff, the surcharge. And that came in lower than expected at 3% and that. So that was about it really. Some other stuff in there. Very bitty budget.
Then we had the Bank of England raise rates yesterday. And that was expected in the market. There was over a 90% probability of that happening. So that didn’t rumble markets and actually the midterms that were on the 3rd of November. News filters out overnight into Wednesday we had this incredible Wednesday. Markets really excited. They were getting much more constrained Trump. Less chaos, less volatility, maybe lower oil, more peace. Maybe this will be the steps to mitigate the conflict in the Middle East. So funds are doing incredible over a week and a half. And then we had this selloff. But you know, it was a really specific selloff.
I put out a message this morning to advisers, and I think what summed up this reversal of excitement into fear was elected Senator Sherrod Brown’s speech saying, “I do not work for the data centers. I do not work for Wall Street.”
This is a huge boon for the US economy, this huge investment, billions upon billions of capital expenditure. And people are now haven’t – they don’t feel like that has trickled down to them because of what they’re paying at the pumps, which is an incredibly visceral thing. When you fill your car up and you see the price go up, even if it’s an extra couple of quid, you feel like a – it does make you mad. Well, apparently makes people mad at politicians. But, the incumbents have been wiped out in the midterms, and now people are worried that this incoming administration won’t be as market friendly as the current president.
So, Nasdaq off -6.5% overnight. It wasn’t doing well anyway. Over the last two weeks it’s down 8.5%.
The S&P was down -4.36% last night and -3.52% over the last two weeks.
MSCI world down -3.28%, -2.32% over the last two weeks.
But every single Courtiers fund is up over that same period.
Leo Hallam
That’s the next point I want to come onto, Jake, is the resilience of the Courtiers funds over this excitement that’s been going on in the world. You know, how, first, are the events affecting what you and the team are doing, looking after the Courtiers funds?
Is it changing anything that you’re doing?
How is it emphasising the diversification that you focus on so heavily and emphasise all of the time, and where are the funds right now?
Jacob Reynolds
I think this is such a great example of what we do in market falls, because everyone expects us to be shifting. And if you have to make a move, then you’ve already made a mistake, right?
So we’ve been talking about this for years, and I think at the 2024 seminars I was on my feet and we were talking about taking a little bit of our S&P 500 exposure and putting it into the S&P Equal Weight. And that was a much more responsible thing to do. We were mitigating the risk of this specific trade.
You know, it’s changed name a lot, right? It was big tech. It was FANGs. Now it’s AI. Now it’s data centres. But it’s all really the same thing, and it’s the same similar stocks all at the top.
We knew it was a specific risk and there was a lot of correlation, so we were just trying to mitigate that within the funds. We said being prudent plays. And when you look at the long run of the equal-weighted S&P 500 versus the market-cap weighted, when you get concentrated into the biggest, most expensive companies, the equal weighted outperforms.
Yet everyone’s piling into the S&P 500, but that’s because it’s liquid, and there’s obviously something to be said for liquidity.
Now we be prudent by taking even more diversification. We have some of the equal weight, we have some of the Russell 1000 Value, and we have some of the S&P Small Caps, the smaller companies in the US, which are trading at a discount to their larger counterparts. And that’s not normal. So allocate something to that.
So that is why we’ve been resilient the last few days, and it’s really from what we’ve been building over years.
But what do we do when things start to sell off? We’re looking for buys, right? There are some tech stocks now that are at the top of our model. We haven’t made the allocation, so you know, you don’t want to talk about names.
This is what we do in downturns. We go out shopping because we’re not looking to sell. The market’s already moved. So, you know, you should have covered off the risk and hopefully you can get the baskets out. If it rains gold, go out with bathtubs, not teaspoons, right? So you’ve got to go and see what’s attractive now. That’s what we’ll be doing this morning.
Leo Hallam
Thanks, Jake. That’s great. Well look, it’s an ongoing story, so we’ll pick up next week, no doubt. Keen to get this out to our client base now, so thank you very much for your time and jumping onto a call without any notice. Much appreciated, and I’ll catch up with you again next week.
If you have any questions, please speak to your Courtiers Adviser or contact us.